
Financial Planning in Your 30s: The Complete Roadmap to Building Wealth in India
- Raghav Gupta
- Aug 19
- 11 min read

Your 30s often come with a strange financial contradiction.
Your income may be higher than ever, yet your financial decisions can feel more complicated than they did in your 20s.
There may be a home loan, family responsibilities, insurance premiums, investments, tax decisions, children's future, ageing parents and retirement all competing for attention at the same time.
And while you may already have a SIP running or money sitting in a savings account, one important question remains:
Are all your financial decisions working together toward the life you actually want?
That is the real purpose of financial planning.
Financial planning in your 30s isn't simply about investing more money. It is about creating a coordinated strategy for your income, expenses, protection, debt, investments, taxes and long-term goals.
Because earning more money doesn't automatically create wealth.
A well-structured financial plan does.
Why Your 30s Are a Critical Decade for Financial Planning
Your 30s can be the stage when several major financial responsibilities begin arriving together.
You may be:
Growing rapidly in your career
Getting married or starting a family
Buying a home
Taking on a long-term loan
Supporting parents
Planning for children's education
Building investments
Paying higher taxes
Thinking seriously about retirement
At the same time, lifestyle expenses often increase alongside income.
This creates a common problem: financial decisions start happening independently.
You buy insurance because someone recommended it.
You start a SIP because your colleague is doing it.
You invest in tax-saving products at the end of the financial year.
You take a home loan based on what the bank approves.
You save whatever is left at the end of the month.
Each decision may appear reasonable on its own. But that doesn't necessarily mean they form a coherent financial strategy.
A strong financial plan connects these decisions.

What Does Financial Planning Actually Mean?
Financial planning is much broader than choosing investments.
At its core, it is the process of understanding your current financial position, defining your future goals and creating a strategy to move from one to the other while managing risks along the way.
A comprehensive financial plan can involve:
Cash-flow management
Emergency planning
Insurance and risk protection
Debt management
Investment planning
Asset allocation
Tax planning
Retirement planning
Goal-based investing
Portfolio review and rebalancing
SEBI's investor education resources similarly emphasise defining financial goals, considering risk and time horizons, diversifying investments and reviewing portfolios as circumstances change.
The important point is this:
Financial planning is not about finding one perfect investment. It is about making different financial decisions work together.
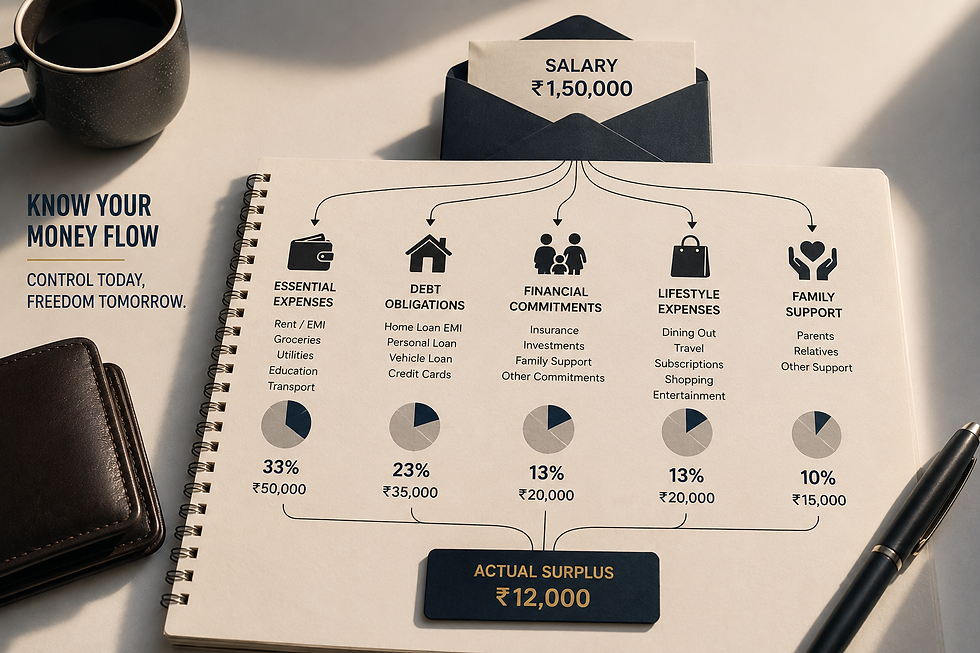
1. Start With Your Cash Flow, Not Your Investments
One of the most common mistakes people make in their 30s is jumping straight into investments. The first question should actually be:
Where is my money going?
Start by mapping:
Income
Your salary, business income, freelance income, bonuses and other predictable sources.
Essential expenses
Rent or EMI, groceries, utilities, education, transportation and other necessary expenses.
Lifestyle expenses
Dining out, travel, subscriptions, shopping and discretionary spending.
Debt obligations
Home loans, personal loans, vehicle loans, credit-card balances and other EMIs.
Financial commitments
Insurance premiums, investments, family support and other recurring obligations.
Once you see the entire picture, you can determine how much money is genuinely available for your financial goals.
For example, someone earning ₹1,50,000 a month may appear to have substantial investment capacity.
But if they have:
₹50,000 in household expenses
₹35,000 home-loan EMI
₹15,000 family support
₹10,000 insurance and other commitments
₹20,000 lifestyle expenses
The right investment amount is therefore not determined by income alone. It is determined by your overall financial position and goals.
2. Build an Emergency Fund Before Chasing Returns
Investments are designed to help you build wealth. An emergency fund serves a different purpose:
It protects your financial plan when life doesn't go according to plan.
Job loss, unexpected medical expenses, urgent family requirements or major repairs can disrupt even a well-designed investment strategy.
Without adequate liquidity, you may be forced to:
Sell investments at an inconvenient time
Take expensive debt
Use credit cards
Pause important financial goals
A common rule of thumb is to maintain several months of essential expenses in easily accessible reserves. But the right amount isn't identical for everyone.
Someone with a stable government job and no dependents may have different liquidity requirements from a self-employed professional supporting a family.
Your emergency fund should therefore reflect factors such as:
Income stability
Number of dependents
Monthly essential expenses
Existing debt
Insurance coverage
Job or business risk
The objective isn't to maximise the return on your emergency fund.
The objective is to make sure the money is available when you need it.

3. Protect Your Wealth Before Trying to Grow It
Investing can build wealth.
Insurance helps protect the financial plan that creates and preserves that wealth.
This is why protection should be considered before aggressively increasing investment risk.
Health Insurance
Employer-provided health insurance can be useful, but depending entirely on it may leave gaps if you change jobs or your coverage isn't sufficient for your family's needs.
Your health insurance strategy should consider:
Your age
Family members
Existing coverage
Medical inflation
Hospitalisation costs
Employer dependency
Term Insurance
If your income supports a spouse, children or parents, your ability to earn is itself a financial asset.
The purpose of term insurance is therefore not simply to buy a large policy because someone recommended a particular number.
The amount of cover should be considered in relation to:
Income
Outstanding liabilities
Dependents
Future financial goals
Existing assets
Children's education
Family's financial requirements
The bigger principle is simple:
A financial plan is incomplete if one unexpected event can undo years of wealth creation.

4. Manage Debt as Part of the Bigger Financial Plan
Debt isn't automatically good or bad. The more useful question is:
Does your debt support your financial goals without putting excessive pressure on your cash flow?
Consider the difference between:
High-interest credit-card debt
A personal loan
An education loan
A vehicle loan
A home loan
Each has a different cost, purpose and impact on your financial position. For example, aggressively investing while carrying expensive high-interest debt may not always be the most efficient strategy.
On the other hand, automatically trying to eliminate every low-cost loan at the expense of long-term investments may also not be appropriate for every household.
Debt decisions need to be evaluated alongside:
Cash flow + interest cost + liquidity + investments + goals + risk.
This is why debt management shouldn't happen in isolation.

5. Turn Financial Dreams Into Specific Goals
“Build wealth” is a good intention. It isn't a financial goal. A financial goal needs greater clarity.
For example:
Goal | Time Horizon | What Needs to Be Planned |
Emergency fund | Short term | Liquidity |
Home down payment | 3–7 years | Capital preservation + growth |
Child's education | 10–15 years | Long-term goal-based investing |
Retirement | 20–30+ years | Long-term wealth creation |
Financial independence | Depends on goal | Corpus + cash-flow planning |
Once your goals are defined, investment decisions become much more meaningful.
Instead of asking:
“Which investment will give me the highest return?”
you can ask:
“What strategy gives this particular goal the best chance of being achieved within its time horizon and risk constraints?”
That is a fundamentally better question.

6. Invest According to Your Goals, Not Market Trends
Your 30s are often when your investment capacity begins increasing. But higher income can also create another problem: Mutual funds, stocks, fixed deposits, bonds, gold, real estate, NPS and other financial products all compete for your attention.The temptation is to ask which product is “best.” But there is no universally best investment.
The right strategy depends on:
Your financial goals
Time horizon
Risk tolerance
Existing portfolio
Liquidity requirements
Tax position
Income stability
Overall asset allocation
For example, money required for a short-term goal should generally not be exposed to the same level of market risk as money intended for a retirement goal several decades away.
This is why goal-based investing is more useful than simply collecting financial products.
A portfolio should have a purpose.

7. Make Tax Planning Part of the Bigger Picture
Tax planning often becomes a last-minute activity. As the financial year approaches, people start asking: “Where can I invest to save tax?”
That approach can lead to unnecessary investments. Tax efficiency matters, but a tax-saving benefit shouldn't be the sole reason for making a financial decision.
A better approach is to consider taxation alongside:
Income
Investments
Financial goals
Cash flow
Risk
Existing assets
Retirement planning
The tax regime you choose and the deductions or exemptions available to you can change over time. Tax rules should therefore always be evaluated using the applicable rules for the relevant financial year.
Tax planning should support your financial strategy "not dictate it".

8. Start Retirement Planning Earlier Than You Think
Retirement can feel extremely far away when you're in your 30s.That's precisely why this is one of the best times to plan for it.The earlier you start, the more time your investments have to potentially compound.
But retirement planning isn't simply: “Invest X amount every month and you'll have ₹1 crore.”
The number you actually need depends on your circumstances.
You need to consider:
Current lifestyle expenses
Expected inflation
Current age
Desired retirement age
Expected retirement lifestyle
Existing investments
Future income
Expected investment returns
Retirement duration
Consider a person who currently spends ₹80,000 a month.Their retirement requirement isn't determined by today's ₹80,000 alone. Inflation can significantly change the cost of maintaining a similar lifestyle decades from now. That is why retirement planning should begin with the future lifestyle you want, rather than a random corpus number.

9. Plan for the Life You Actually Want
Financial planning isn't just about maximising your investment corpus.
Money is ultimately a tool for creating choices.
You may want to:
Buy a home
Travel regularly
Support your parents
Fund your child's education
Start a business
Retire early
Work because you want to, rather than because you have to
Build wealth for the next generation
A financial plan should account for these priorities. This is also why copying someone else's investment strategy can be dangerous.Your colleague's salary, family responsibilities, debt, risk tolerance and goals may be completely different from yours.
Your financial plan should be personal because your financial life is personal.

10. Review Your Financial Plan as Your Life Changes
A financial plan isn't something you create once and forget. Your circumstances change:
You get a salary increase.
You switch jobs.
You get married.
You have a child.
You buy a house.
You take a loan.
Your parents' financial requirements change.
Markets move.
Tax rules change.
Your goals evolve.
Every major life event can change the assumptions behind your financial plan.
This is why portfolio and financial-plan reviews matter. A portfolio that was appropriate five years ago may no longer match your current goals, risk profile or time horizon.

The Biggest Financial Mistake in Your 30s
It isn't necessarily not investing enough. It isn't necessarily having too much debt. It isn't even necessarily choosing the wrong investment.The bigger problem is making financial decisions in isolation.
Think about the connections:
Your income determines your cash flow.
Your cash flow determines how much you can save and invest.
Your goals determine when you need the money.
Your time horizon influences your investment strategy.
Your risk tolerance influences your asset allocation.
Your insurance protects your financial plan.
Your debt affects your cash flow.
Your tax strategy affects your effective returns.
Your retirement goal determines how much long-term wealth you need.
Everything is connected and when these decisions are managed separately, it becomes difficult to know whether your overall financial strategy is actually moving you toward your goals.
Why a Holistic Financial Plan Matters
This is where financial planning becomes different from simply investing.
Imagine you have:
Three mutual fund SIPs
Some stocks
EPF
An FD
Employer health insurance
A term insurance policy
A home loan
On paper, you may appear financially organised.
But the real questions are:
Are your investments aligned with your goals?
Do you have adequate protection?
Is your debt affecting your investment capacity?
Are your assets appropriately allocated?
Are you investing enough for retirement?
Are your tax decisions aligned with your overall strategy?
What happens if your income stops unexpectedly?
Are you on track for the financial life you actually want?
Answering these questions requires looking at the whole financial picture, not just one investment account.
How Improwise Helps You Build a Financial Plan That Works Together
This is where professional financial planning can make a meaningful difference.
At Improwise, the approach is built around looking at your financial life as a connected system rather than treating investments, insurance, taxes and debt as separate decisions.
The process can bring together areas such as:
Financial Planning
Understanding your current financial position, defining your goals and creating a personalised roadmap.
Investment Management
Building and managing an investment strategy around your goals, risk profile and time horizons.
Portfolio Review
Evaluating existing investments to understand whether they continue to serve their intended purpose.
Tax Planning
Looking for ways to improve tax efficiency while keeping your broader financial strategy in view.
Insurance Planning
Assessing whether your protection strategy is appropriate for your income, liabilities and dependents.
Debt Management
Evaluating liabilities and identifying ways to manage debt more effectively within your overall financial plan.
Cash-Flow Planning
Understanding where your money is going and how your income can be allocated toward present needs and future goals.
The objective isn't simply to help you buy another financial product.
It is to help you understand how all your financial decisions fit together.

A Simple Financial Planning Checklist for Your 30s
Before considering your financial plan complete, ask yourself:
Do I know my monthly cash flow?
Do I have an adequate emergency reserve?
Is my health insurance sufficient?
Do my dependents have adequate financial protection?
Do I have a clear plan for my debt?
Have I defined my major financial goals?
Are my investments linked to specific goals?
Is my asset allocation appropriate for my risk and time horizon?
Am I planning for retirement early enough?
Am I making tax decisions as part of a larger strategy?
Do I review my portfolio regularly?
Do I know whether my current financial strategy is actually on track?
If several answers are uncertain, the problem may not be that you need another investment.
You may need a better financial plan.
Frequently Asked Questions
What is financial planning in your 30s?
Financial planning in your 30s involves organising your income, expenses, emergency savings, insurance, debt, investments, taxes and long-term goals into a coordinated strategy.
How much should I invest in my 30s?
There is no single percentage that works for everyone. The appropriate amount depends on your income, expenses, debt, existing assets, financial goals, time horizon and risk profile.
Is starting a SIP enough for financial planning?
A SIP can be one part of an investment strategy, but it doesn't constitute a complete financial plan. A broader plan may also need to consider cash flow, emergency savings, insurance, debt, taxation, asset allocation and retirement goals.
How much emergency fund should I have?
The appropriate emergency reserve depends on factors such as monthly essential expenses, income stability, dependents, debt and insurance coverage. A commonly used starting point is several months of essential expenses, but the appropriate level should be personalised.
Should I invest or repay my home loan?
There isn't a universal answer. The decision depends on factors including the loan interest rate, investment opportunities, liquidity needs, risk tolerance, tax considerations and your broader financial goals.
When should I start retirement planning?
The earlier you start, the more time you have to build a retirement corpus. Your 30s can be an important period to establish a long-term retirement strategy because you potentially have several decades before retirement.
When should I consider working with a financial planner?
If your finances have become more complex—multiple investments, loans, insurance policies, tax considerations, dependents or competing financial goals—a financial planner can help bring those decisions together into a coordinated strategy.

Your 30s Don't Need More Financial Products. They Need More Financial Clarity.
Building wealth isn't simply about finding the highest-return investment.
It's about making sure the money you earn today supports the life you want tomorrow.
Your investments, insurance, debt, taxes, cash flow and financial goals are interconnected. When they are planned separately, important gaps can easily go unnoticed.
When they are brought together into one strategy, your financial decisions become much clearer.
That's the role of holistic financial planning.
If you're in your 30s and want to understand where you stand financially, what you're working toward and whether your current strategy is taking you there, Improwise can help you bring the entire picture together.
Because the goal isn't simply to invest more.
The goal is to make your money work together—for the life you're building.
Disclaimer
This article is intended for educational and informational purposes only and should not be considered personalised financial, investment, insurance or tax advice. Financial decisions should be made after considering your individual circumstances, objectives, risk profile and applicable laws and regulations. Tax rules and financial regulations may change, so current official sources and professional advice should be consulted before making financial decisions.


Comments